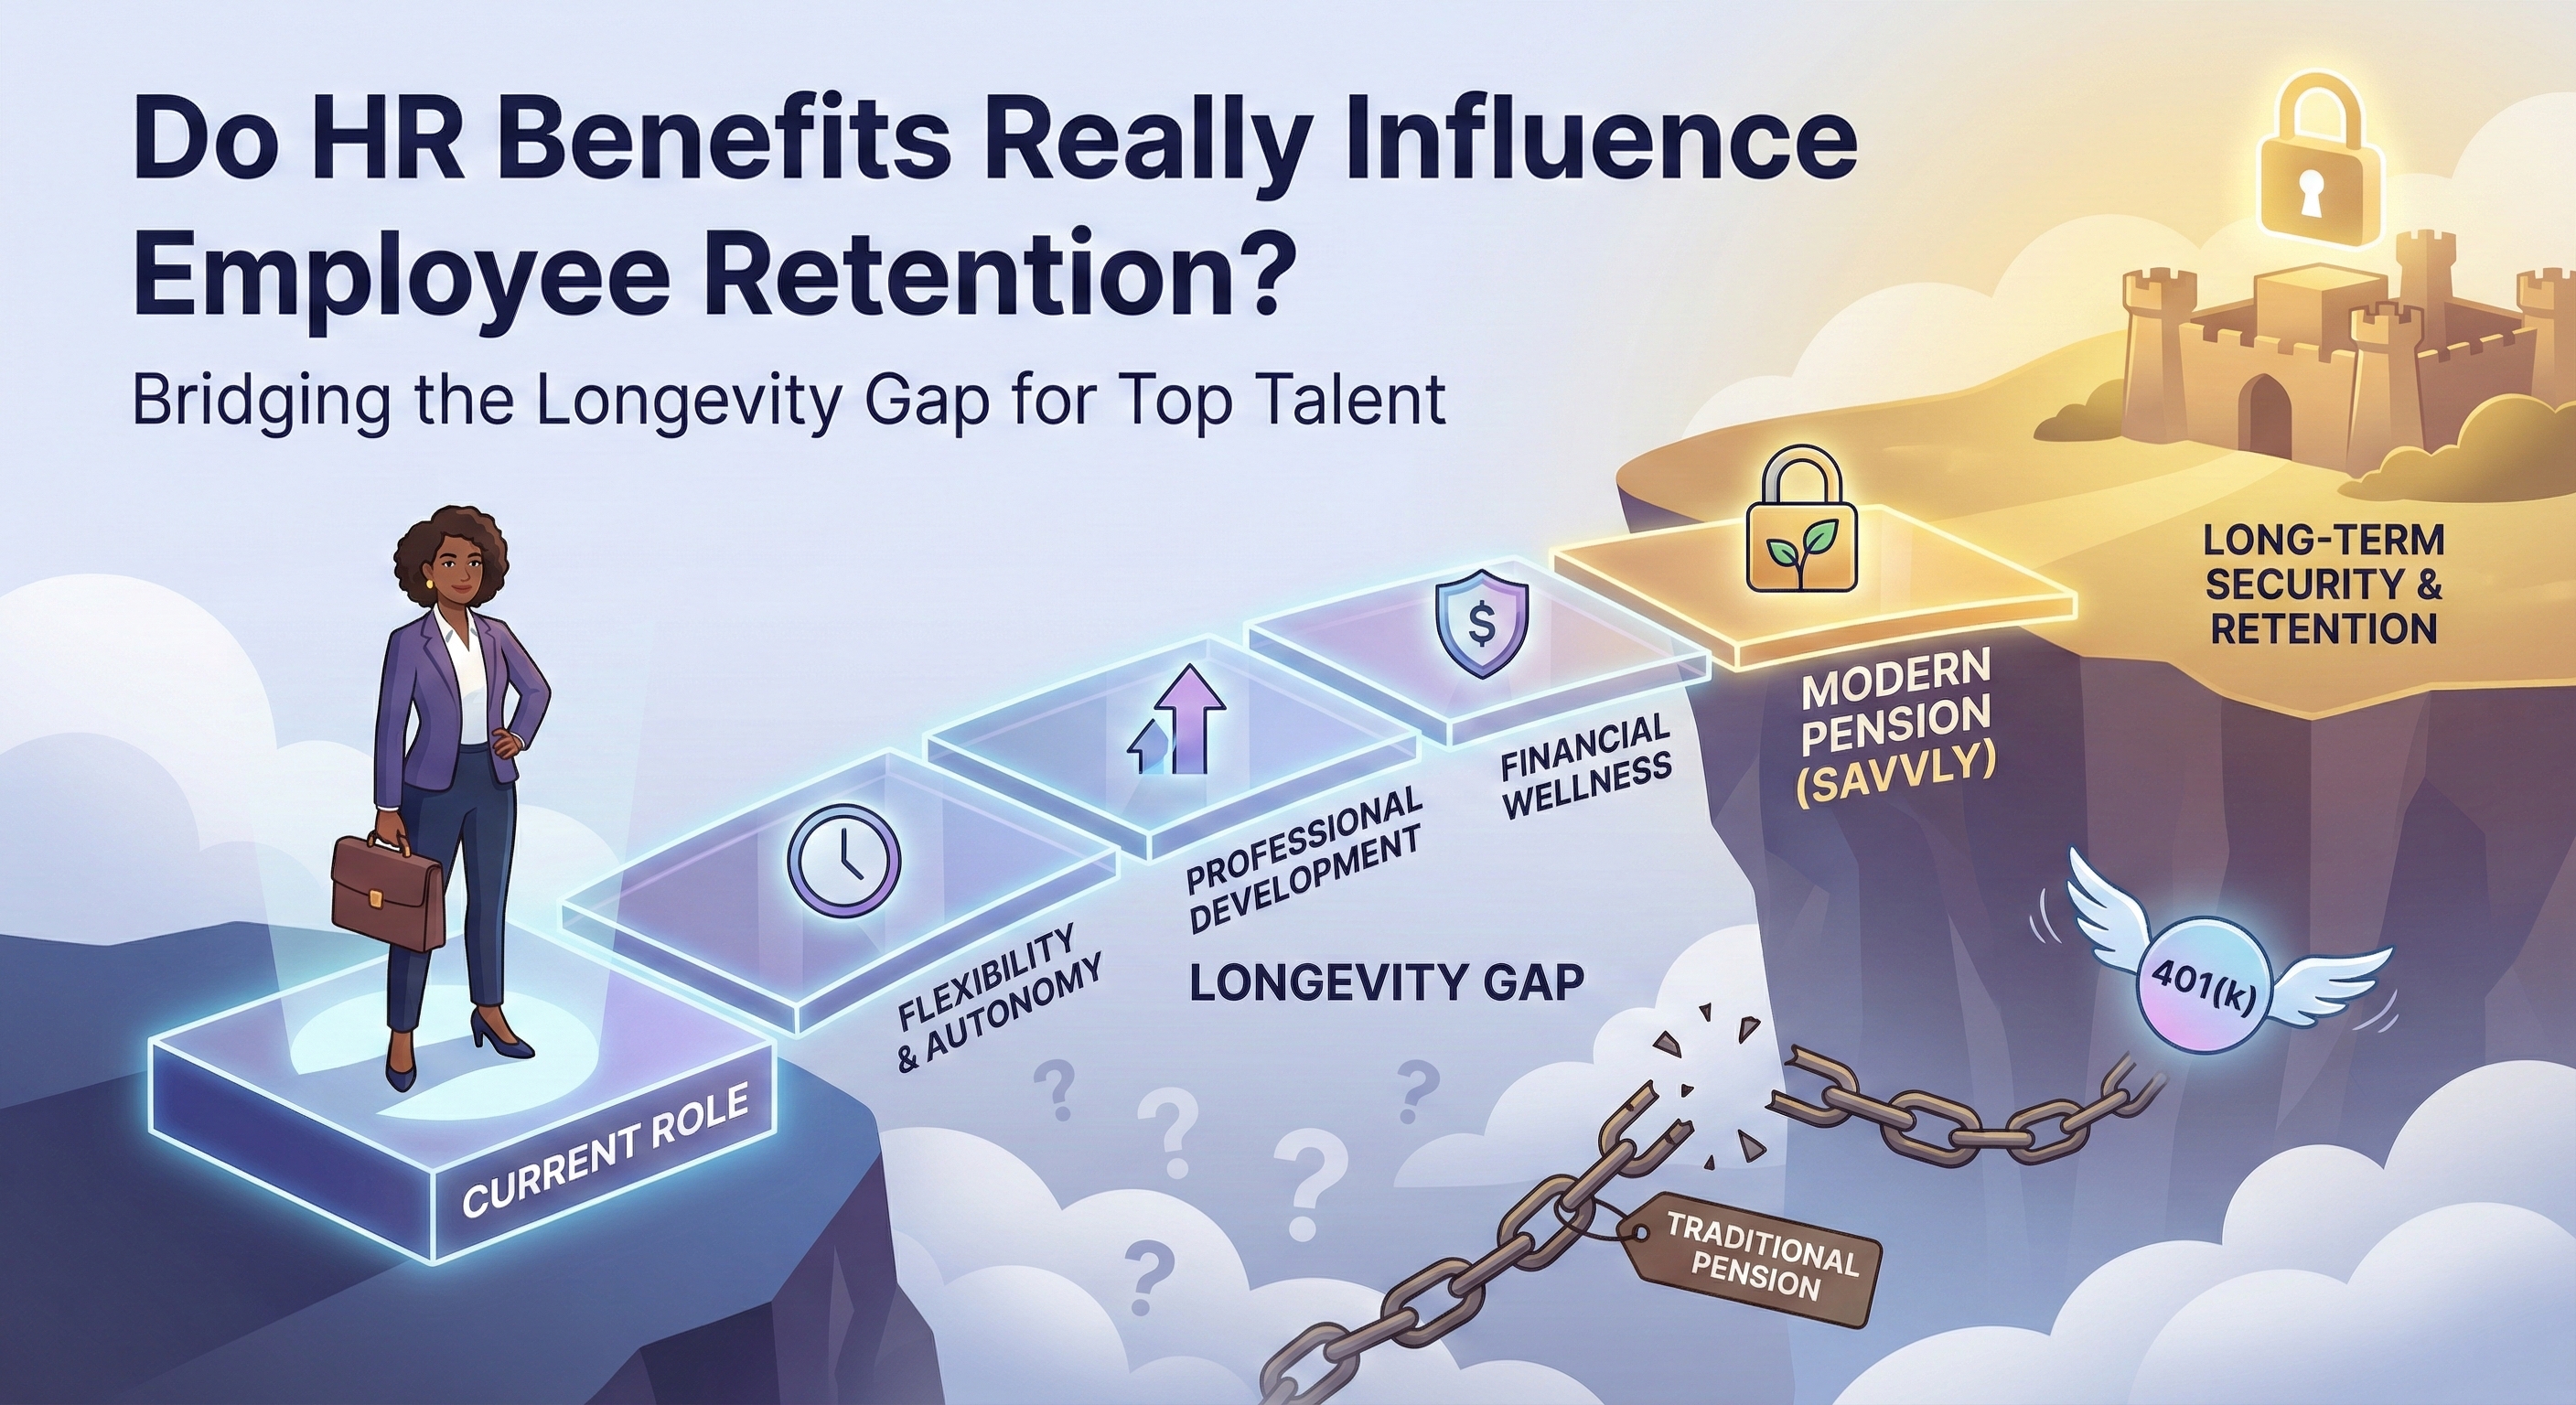
A 401(k) is one of the best tools available for building retirement savings. It was never built to answer a different question: what happens if you live to 95?
Most 401(k) plans are shaped around a familiar retirement, save for around 40 years, then draw down for 20 to 30. But the IRS requires withdrawals to begin at age 73, and the math behind most retirement calculators quietly assumes the money needs to last into the mid-80s or 90s, not much further. For the growing number of people living well past that, a gap opens up right where a 401(k)'s design starts to run thin.
A 401(k) is an accumulation tool. Contributions grow tax-deferred, often with an employer match, and the account is meant to compound for decades before retirement begins.
By retirement age, the numbers vary widely. Fidelity's Q2 2026 data, drawn from 26,800 corporate retirement plans, puts the average 401(k) balance for Baby Boomers at $260,300. Vanguard's analysis of nearly 5 million 401(k) plans found a median balance of $87,571 for savers ages 55 to 64, well below the average of $244,750 for that same group, a reminder that averages can be pulled upward by a smaller number of large accounts. Whatever the number, the plan's job ends in the same place: it hands the retiree a balance and a withdrawal strategy, then steps back. That balance often moves with the retiree too. Anyone who has changed jobs and had to decide what to do with an old 401(k) knows the accumulation phase is rarely a straight line.
The first sign of the gap is procedural. Required minimum distributions begin at 73, pulling roughly 3.77% of the account's value in the first year and increasing as a percentage each year after, whether or not the retiree still needs the income at that pace.
The deeper gap is about time horizon. A common planning assumption, known as the 4% rule, is built around the idea that a portfolio needs to last about 30 years, carrying a 65-year-old retiree to around 95. That's a reasonable target for a healthy share of retirees, but it also assumes steady markets, no major health costs, and a withdrawal rate that's difficult to hold to in a downturn. A 401(k) has no built-in mechanism for what happens if any of those assumptions break, or if the retiree simply lives longer than the plan anticipated.
A longevity benefit is not a replacement for a 401(k). It's a second layer, contributed to separately, designed to add potential income at the ages a 401(k) was never built to plan around.
The Savvly Longevity Benefit works this way: investors contribute monthly, starting at $10 a month, into a shared fund invested in the S&P 500. There is no rollover required and no change to an existing 401(k), IRA, or Roth IRA. When an investor exits early, their unused share may be reallocated to those who stay, and the fund is designed to pay out at 80, 85, 90, and 95 for investors who reach those milestones.
The two accounts do different jobs at different points in a retirement. A 401(k) funds the early, most predictable years. A longevity benefit is built for the years further out, when a 401(k)'s original 20- or 30-year plan is furthest from where it started.
If a 401(k) answers "how much have I saved," a longevity benefit answers a different question: "what happens if I'm still here at 90?" Neither one replaces the other. Used together, they cover more of retirement than either does alone.
The Savvly Longevity Benefit is designed to help investors build potential income for the later years of retirement. It adds a longevity-based reallocation layer to market-linked performance, creating the opportunity for potential cash payouts at ages 80, 85, 90, and 95 for investors who reach those milestones. Savvly is not insurance, not a guaranteed product, and not FDIC insured. Learn more at savvly.com/disclosures.
Do I need to roll over my 401(k) to use a longevity benefit?
No. The Savvly Longevity Benefit is a separate contribution, not a rollover. An existing 401(k) or IRA stays exactly as it is.
Can I contribute to a 401(k) and a longevity benefit at the same time?
Yes. They're designed to work alongside each other, not in place of one another.
Does a longevity benefit replace my 401(k)?
No. A 401(k) is built for accumulation and the early years of retirement. A longevity benefit is built to add income at later milestone ages.
This article is for informational purposes only and does not constitute financial, tax, or investment advice. Consult a qualified financial professional before making retirement planning decisions.
Disclosures
The information on this page is provided for educational purposes only and is not intended as investment, legal, or tax advice. It is designed solely to illustrate how longevity-linked investment benefits may work under certain assumptions. Actual results will vary. All illustrations, examples, and case studies are hypothetical and are intended to demonstrate potential scenarios — not to predict or guarantee actual outcomes. They do not represent the performance of any individual investor, portfolio, or account.
Key Assumptions Used in the Illustrations
Life expectancy and mortality projections are based on the most recent Social Security Administration (SSA) tables available at the time of simulation.
In the event of death or early withdrawal, hypothetical scenarios assume that investors who exit early, or their estate in the event of death, may receive 75% of the lesser of the initial investment or current market value, plus 1% for each full year the account was active. Case studies assume standardized market growth of 8% annually and do not incorporate unexpected market volatility, inflation, changes in interest rates, or changes in an investor's personal circumstances.
Simulations may assume a 3% annual early withdrawal rate prior to payout or death. All figures shown are net of fees. No forecast, projection, or hypothetical return should be relied upon as a promise or representation of future performance.
Past performance is not indicative of future results. The 8% annual market growth rate used in illustrations is a standardized assumption for modeling purposes only and does not represent the historical or expected performance of any specific investment. Note that early or voluntary withdrawals by other participants can affect fund performance and the size of distributions, and that a higher-than-expected number of participants reaching payout milestones may reduce the per-participant benefit received.
The Savvly Longevity Benefit is not a bank product, not FDIC insured, not insured by any federal government agency, and not insurance; payout amounts are not guaranteed. Investment values may decline..
The Savvly Longevity Benefit may not be suitable for all investors. Eligibility to invest is subject to qualification requirements and not all investors will be eligible. Investors should carefully consider their investment objectives, risk tolerance, time horizon, and financial situation before investing. See savvly.com/disclosures for current eligibility criteria, fees, risks, withdrawal terms, and fund assumptions.
This content is published by Savvly, Inc. Savvly has a financial interest in the products described and this content should not be interpreted as independent financial research or analysis. Investors should carefully evaluate their own circumstances and consult a qualified financial professional before making any investment decision.